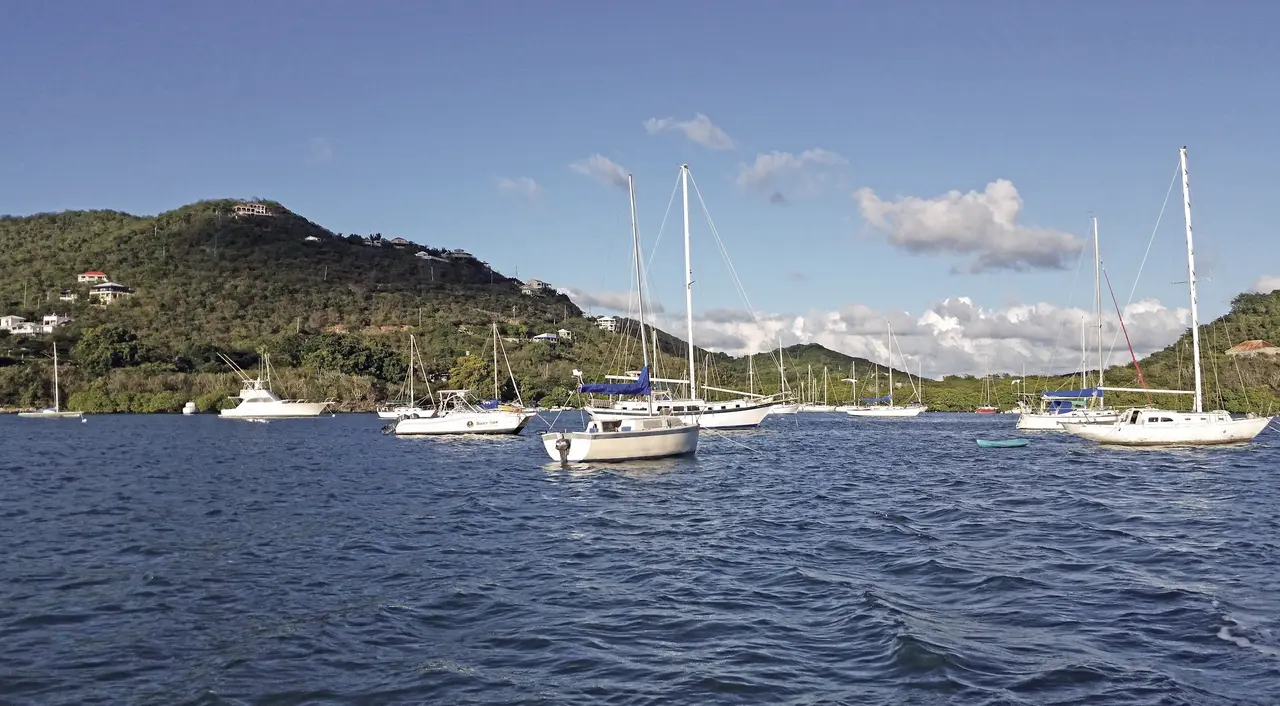
St. John, U.S. Virgin Islands
St. John tax preparation, without the trip off island
We have no office on St. John. We prepare U.S. Virgin Islands returns for St. John businesses and residents from St. Thomas, and Rodd Goldman, CPA, CFE, sees clients in person on all three islands when a matter calls for it.
Filing from St. John no longer means a boat ride
VIBIR’s remittance addresses for gross receipts payments are on St. Thomas and St. Croix, which used to mean a boat ride to hand over a check. Now VIBIR runs a gross receipts e-filing portal at gross-receipts.bir.vi.gov, and VI Quick File opened for income tax in February 2025, so a St. John business can file and pay without leaving the island. What remains is getting the numbers right and knowing which returns are due, which was always the real work.
- Books, statements and sales summaries come to us through your client portal
- Reviews and planning happen by video or phone
- Returns with tax due are filed and paid online with VIBIR
- We meet in person when it is warranted, on your island or ours
Short-term rentals owe two territorial taxes
A villa or apartment rented by the week owes two territorial taxes, on two separate forms.
The hotel room tax is 12.5% of the gross room rate on stays under 90 days, collected from the guest and remitted by the operator on Form 722 V.I. by the 30th of the following month. Energy and maintenance surcharges are inside the taxable rate; food, beverage and gratuities are outside it. The rate went from 10% to 12.5% on January 1, 2016.
The gross receipts statute also names rentals in its base by express terms, so the same rental operation can owe both, on two different forms. If you have been filing only one, start there.
A timeshare unit adds a third item: a $25 per night environmental and infrastructure fee, remitted on Form 722EI, in effect since May 1, 2017.
If you moved to St. John
Where you file turns on bona fide residency under IRC § 937, which requires three things: presence, tax home and closer connection. Presence can be met several ways, the most familiar being 183 days in the territory during the year. Form 8898 is required for the year residency begins or ends.
Meet all three for the whole year and you file with VIBIR only. The year of the move has its own rules, so get advice before it closes. Fall short while holding Virgin Islands source income and you file on both sides, the same Form 1040 to the IRS and to VIBIR, with Form 8689 allocating the tax between them. The case law on residency is unforgiving where the facts are thin.
One routing detail catches new employers: FICA and FUTA on Virgin Islands wages go to the IRS, not VIBIR, even though the income tax return goes to VIBIR.
Where to go next
Find out which St. John returns you owe.
We’ll work out what is due, what is late, and what it takes to get straight with the Bureau.